As voters weigh the economic records of both parties ahead of the midterms, cost-of-living concerns have emerged as a defining issue. Some point to the 40-year high inflation under President Joe Biden while others blame President Donald Trump’s tariff policies and the conflict in Iran.
Democrats fault Trump for high gas prices and other expenses, while voters compare the cost-of-living differences between blue and red states.
As both parties trade blame for rising costs, here is a look at where their economic track records actually stand.
Trump and Biden
Throughout his 2024 campaign, Trump routinely promised to bring down inflation and restore affordability, and before the war in Iran began in late February, headline consumer inflation in the United States had been inching closer to the Federal Reserve’s elusive 2 percent target.
However, the inflation outlook changed significantly once the conflict broke out and disrupted traffic through the Strait of Hormuz, driving up global energy prices.
Now approaching its ninth month, the war has kept the annual inflation rate in the United States persistently above 3 percent.
While energy-driven price hikes mirror the challenges the previous administration faced, Biden contended with an even more severe inflation shock. Under his presidency, annual inflation peaked at a 40-year high of 9.1 percent in June 2022, becoming a major vulnerability for his economic record. The annual inflation rate was 1.4 percent when he took office in January 2021.
Critics, including Republicans in Congress, blamed his energy policies for the rise in prices across the board, from gas stations to grocery stores.
Soon after taking office in 2021, Biden signed several executive orders targeting the fossil fuel industry, including canceling the Keystone XL pipeline permit and pausing new oil and gas leases on federal lands.
In response, energy companies curbed investments and scaled back expansion plans. Supply constraints unsettled energy markets, driving oil and gas prices significantly higher throughout 2021 and 2022.
Some prominent economists, including former Democratic Treasury Secretary Larry Summers, also pointed to the $1.9 trillion American Rescue Plan as a driver of inflation during Biden’s presidency. The stimulus plan was intended to prevent a post-pandemic recession.
Prominent economist Mohamed El-Erian criticized the plan, warning it would overheat the economy and cause damaging levels of inflation. Despite these warnings, Biden signed the stimulus package into law in March 2021. Inflation quickly climbed from 2.6 percent that month to 7 percent by the end of 2021.
Under Biden, the national average gas price reached an all-time high of $5.02 in 2022. It was not until late 2025, during the second Trump administration, that the national average slipped below $3.
Gas prices later surged in 2026 as crude oil climbed toward $100 a barrel in response to the war in Iran. This pushed the national average to about $4.50 per gallon in May 2026, the highest level of the year so far. Since then, prices have moderated somewhat, with the national average standing at about $4.27 per gallon on Oct. 27.
When gas prices began to surge in 2021, Biden initially dismissed the inflation as “transitory.” He blamed Russia’s invasion of Ukraine in February 2022 for rising prices. As prices kept rising, he began accusing companies of price gouging.
The consumer price index (CPI) increased by an average of 5 percent per year during Biden’s presidency, compared to 1.9 percent annually during Trump’s first term. To date, average annual inflation under Trump’s second term has been nearly 3 percent.
Cumulatively, the CPI rose by more than 21 percent during Biden’s four-year term, compared to 7.7 percent during Trump’s first term. And since Trump began his second term, overall prices have risen by about 6 percent in total.
Although inflation slowed down toward the end of the Biden administration, the cumulative effect sapped workers’ wages. Real (inflation-adjusted) earnings declined for more than two years, which eroded the public’s purchasing power and applied financial pressures on families.
Despite headwinds ranging from the Iran war to expansive new tariffs, inflation under the Trump administration has run lower than during Biden’s presidency. Furthermore, underlying inflation has been tame: Stripping out volatile energy and food prices, the annual core inflation rate came in at 2.6 percent in September.
Yet almost two years into Trump’s presidency, Americans remain deeply frustrated by the cost of living, which continues to shape their views of the broader economy and their choices at the voting booth.
Heading into the midterms, various polls show that Trump’s approval ratings on the economy and inflation are firmly underwater. An Oct. 6 Economist–YouGov poll found that 36 percent of respondents approved of the president’s handling of the economy.
By comparison, Biden had polled better heading into the 2022 midterms. An Economist–YouGov survey from October of that year found that 40 percent approved of Biden’s handling of the economy.
The growing dissatisfaction is also reflected in consumer sentiment.
The University of Michigan’s Consumer Sentiment Index—a widely watched barometer of the public’s confidence in the current and future economic landscape—was 48 in October, the second-lowest reading in its nearly 75-year history. The lowest recording, 44.8, occurred in May of this year.
While sentiment continues to deteriorate, real median income has improved, and the poverty rate has steadily declined in the last few years.
Median weekly earnings of full-time wage and salary workers is up about 4 percent since the first quarter of 2025, according to the Bureau of Labor Statistics.
The Census Bureau reported in September that the official poverty rate dipped to an all-time low of 10.2 percent last year.
According to Deutsche Bank economists, there is a growing disconnect between how consumers feel about the economy and the actual economic statistics.
In a recent note emailed to The Epoch Times, they explained that “households might be responding to the cumulative price/cost of living shock since COVID rather than the spot inflation rate.”
They added that ongoing housing affordability challenges and growing worries about artificial intelligence (AI) are also weighing on consumer sentiment.
“The cost of everything from groceries and gas to housing and childcare is going up because of choices made by Donald Trump’s administration,” former Vice President Kamala Harris wrote in an Oct. 20 post on X.
Speaking at a Michigan rally on Oct. 24, former President Barack Obama similarly blamed Trump’s policies for rising costs, pointing to the war in Iran “that nobody asked for.”
Red and Blue States
Many consumers continue to cite the cost of energy—from gasoline to utility bills—as major concerns heading into the midterms, making affordability a prominent issue for policymakers and political candidates alike.
Regarding prices at the pump, a July report by the Institute for Energy Research (IER) found that in states in which Democrats controlled the governorship and the legislature, gasoline prices averaged $3.69 per gallon, compared with Republican states, where gasoline averaged $3.14 per gallon, a gap of $0.55 per gallon.
According to the report, much of this gap is due to higher gasoline taxes, hostility toward refineries, and other policies that drive up fuel costs.
In addition, activists are bringing dozens of climate lawsuits against energy companies that, if they succeed, could sum to hundreds of billions of dollars in damages for companies that produce or refine oil, gas, and coal.
These costs would likely be passed on to consumers in the form of price hikes.
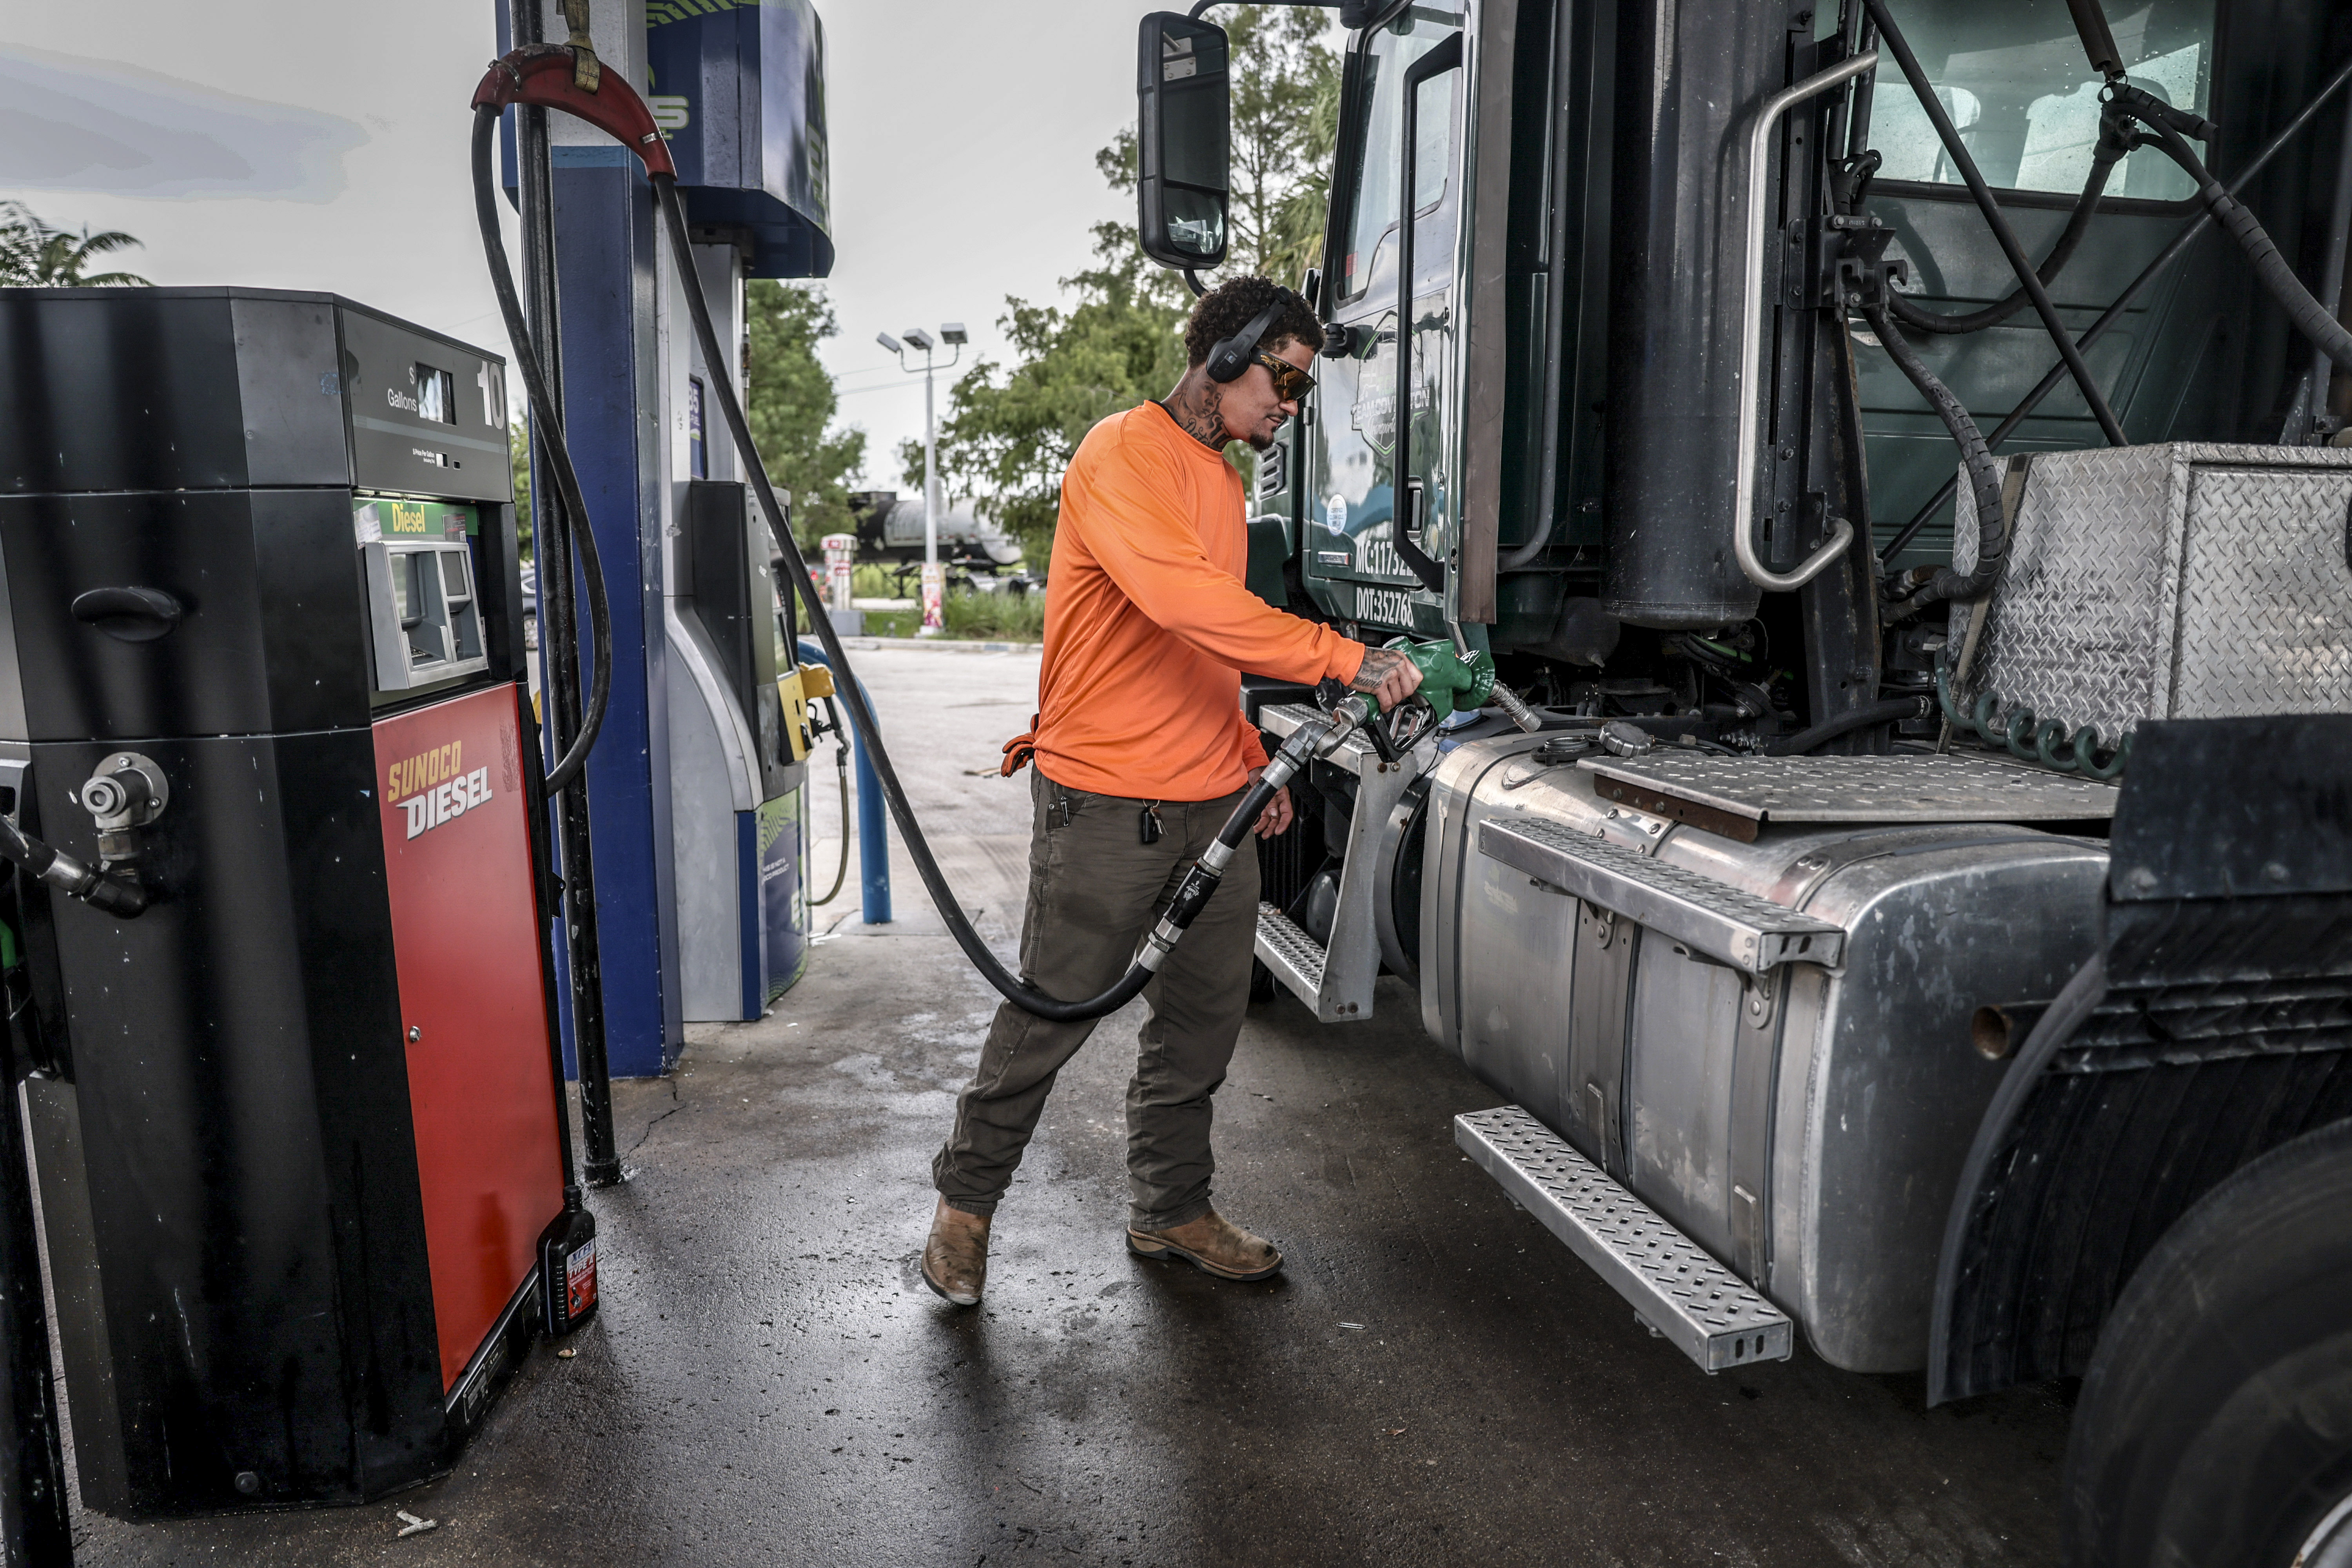
Diesel prices have also rocketed during the Iran conflict. While the fuel cost is down from its record high of almost $6.53 in September, the average price per gallon is still firmly above $6, about 40 percent higher than a year ago.
Regarding electric bills, an IER and Always On Energy Research analysis found that blue-state residents pay, on average, 42 percent more for electricity than red-state residents.
The report attributes this difference to heavy-handed regulation, including net-zero emissions mandates, carbon pricing and cap-and-tax regimes, and other laws intended to replace fossil fuels with wind and solar energy, IER spokesman Alex Stevens told The Epoch Times.
Housing Affordability
Like electricity costs, housing affordability diverges between red and blue states.
According to a 2025 Realtor.com report, the most affordable states for housing are in the South and Midwest.
The report notes that states in the South and West are building the most homes, with seven states in these two regions accounting for more than half of new-home construction permits issued across the country in 2024.
Grading states for affordability, the report says, “States in the South and Midwest received all of the good grades given out (As and Bs) on the basis of affordability and homebuilding; states in the West and Northeast, with generally stricter zoning and land use regulations, received all of the bad grades (Ds and Fs).”
Both the Biden and Trump administrations proposed measures they claimed would improve housing affordability after the unprecedented surge in record home prices following the COVID-19 pandemic. This past summer, lawmakers also passed the most comprehensive housing bill in decades—the 21st Century ROAD to Housing Act.
The legislation included dozens of provisions to boost supply, including streamlining environmental reviews, encouraging states and localities to reform zoning and land-use guidelines, supporting housing modernization, and restricting large institutional investors from buying single-family homes.
“We haven’t built enough homes in this country, so the more we can prioritize supply-side initiatives, ultimately, the more stable and more affordable housing will become,” Frank Cassidy, former Federal Housing Administration commissioner, told The Epoch Times.
Housing starts have not yet returned to pre-2020 levels, and have been trending lower since hitting a 2022 peak. Currently, industry experts say the United States is short 4 million to 5 million homes.
The median sales price of existing properties has steadily increased since falling below $400,000 at the start of the year. August’s median existing-home sales price was $417,500, according to the National Association of Realtors.
Conversely, the median sales price of new houses sold in September was $400,400, up from $398,700 in January, Census Bureau data show.
But the cheaper new homes have not eased the crunch in the larger existing-home market.
Compounding the shortage, higher mortgage rates are pushing up monthly payments even further. The median monthly mortgage payment is almost $2,800—at a 7.4 percent mortgage rate, up more than 8 percent from a year ago, according to Redfin. As a result, many families are priced out of today’s housing market, which may present challenges for the Trump administration.
Interest Rates and Borrowing Costs
Trump has said lower interest rates would be “rocket fuel” for the U.S. economy.
One way to achieve this, according to the president, is for the Federal Reserve to act.
“Because the U.S. economy is so strong, regardless of the Fed’s formula, we should have the lowest interest rates in the world,” Trump told reporters ahead of the Fed’s September policy meeting.
But the central bank, like many of its counterparts, has been heading in the other direction.
The Fed followed through on its first quarter-point rate hike since July 2023 in September, and policymakers and markets alike are penciling in at least one more rate hike to prevent second- and third-order inflation effects.
The Treasury bond market has been in the spotlight since the outbreak of war in the Middle East, with key yields climbing to multi-decade highs.
The benchmark 10-year Treasury yield—a key rate that influences a range of business, consumer, and government borrowing costs—recently closed at its highest level since 2002, trading above 5.3 percent. The 10-year yield has since cooled off, sliding back to around 5 percent.
When Trump began his second term, the 10-year was around 4.6 percent, and it fell to as low as 3.93 percent in October 2025.
Markets will now wait to see whether manufacturers pass higher costs on to consumers, said Jeff DerGurahian, loanDepot’s head economist.
“If those costs begin showing up in both headline and core inflation, mortgage rates could remain elevated,” DerGurahian told The Epoch Times. “But if businesses absorb more of the increases, that could ease inflation concerns and give rates some room to improve.”
Higher interest rates have filtered through the U.S. housing market.
Mortgage rates are at their highest levels in three years, with the average 30-year fixed rate at 7.28 percent in early October, according to Freddie Mac.
The 30-year mortgage rate, which typically tracks the 10-year bond yield, slipped below 6 percent in late February for the first time since 2022.
The longer mortgage rates remain elevated, the harder it will be for younger people—an important voting bloc for the president in 2024—to achieve the dream of homeownership.